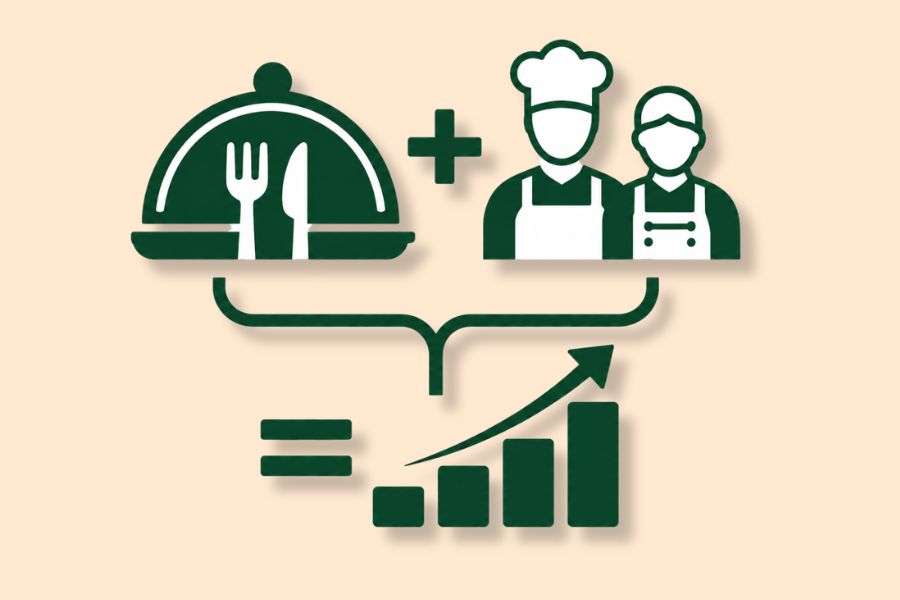
Restaurant prime cost is one of the most useful financial metrics for understanding how efficiently a food service business operates. It combines two major expenses, food and beverage costs and labor costs, providing management with a clearer view of how much revenue is consumed by essential operating activities.
Many restaurant operators monitor ingredient expenses closely but evaluate staffing costs separately. This can make it difficult to understand how both categories influence profitability.
Tracking restaurant prime cost allows businesses to identify cost pressures, improve operational decisions, and evaluate performance using consistent financial information.
What Is Restaurant Prime Cost?
Restaurant prime cost is the combined value of food and beverage cost of goods sold and total labor expenses during a specific period.
Food and beverage costs represent the ingredients consumed to produce the products sold.
Labor expenses include gross wages, employer payroll contributions, overtime, and other relevant employee-related costs, depending on the company’s accounting methodology.
The basic formula is:
Prime Cost = Food & Beverage Cost of Goods Sold + Total Labor Cost
To calculate prime cost as a percentage of revenue:
Prime Cost % = (Prime Cost / Net Sales) × 100
All figures should cover the same reporting period and follow a consistent accounting basis.
Prime cost is particularly useful because its components represent significant costs that management can influence through purchasing, production, scheduling, and operational planning.
How to Calculate Restaurant Prime Cost
Consider a restaurant with the following monthly financial results:
- Net sales: €50,000
- Food and beverage costs: €15,000
- Total labor costs: €17,500
The calculation is straightforward:
€15,000 + €17,500 = €32,500
The prime cost percentage is:
€32,500 / €50,000 × 100 = 65%
This means that 65% of net sales is consumed by food, beverage, and labor expenses.
The remaining 35% must cover rent, utilities, maintenance, administration, and other operating expenses before the business generates its final operating profit.
The calculation provides management with a practical starting point for assessing financial efficiency.
What Is a Good Prime Cost Percentage?
There is no universally appropriate prime cost percentage for every restaurant.
The acceptable level depends on the business model, service standards, pricing strategy, labor requirements, and the structure of other expenses.
A fine dining restaurant may require more employees per guest than a quick-service operation. Meanwhile, a casual dining concept may operate with a different ingredient cost structure.
Industry guidance often refers to indicative prime cost levels around 55% to 65%, but these figures should never be treated as universal performance targets.
A more meaningful assessment compares actual results with historical performance, the operating budget, and benchmarks from businesses with similar characteristics.
For hotels and resorts, prime cost should also be examined by outlet or department where reliable financial data is available.
Why Food Cost Alone Does Not Tell the Full Story
A restaurant may maintain a relatively low food cost percentage while experiencing excessive labor expenses.
This can result from inefficient scheduling, low staff productivity, unnecessary overtime, or mismatches between staffing levels and customer demand.
Conversely, a restaurant with controlled payroll expenses may still experience significant ingredient losses caused by waste, inconsistent portion sizes, or inadequate purchasing procedures.
Both situations can reduce profitability even when one individual cost category appears satisfactory.
This is why structured restaurant financial reporting should examine food and beverage costs alongside payroll and other operating expenses.
Understanding the interaction between these figures supports more informed management decisions.
How Can Restaurants Improve Prime Cost?
Control Food and Beverage Expenses
Accurate recipe costing, standardized portions, inventory monitoring, and supplier price reviews are essential for reducing unnecessary ingredient costs.
Management should also monitor waste, spoilage, and differences between expected and actual consumption.
Improve Labor Scheduling
Staffing levels should reflect customer demand, operating hours, seasonal patterns, and the specific requirements of each service period.
Effective scheduling helps businesses avoid unnecessary labor expenses while maintaining consistent service standards.
Increase Operational Productivity
Clear responsibilities, staff training, and documented operating procedures support more efficient daily operations.
Improving workflows can reduce repeated tasks, delays, and operational mistakes without automatically requiring reductions in staff.
Monitor Costs Consistently
Prime cost should be reviewed alongside revenue, customer volume, average spend, and productivity indicators.
The purpose is to understand why financial results change and which areas require corrective action.
HORECA Plus addresses similar operational challenges through structured cost analysis and business improvement planning, as reflected in its hospitality and restaurant project scenarios.
How Often Should Prime Cost Be Reviewed?
Monthly reporting provides the foundation for evaluating overall financial performance.
However, weekly reviews can help restaurants detect cost changes earlier, particularly when ingredient prices fluctuate or staffing requirements vary significantly.
Labor expenses can be monitored through scheduled and actual working hours, while food and beverage costs require reliable purchasing and inventory information.
The most important requirement is consistency. Comparing figures calculated using different methods or reporting periods can produce misleading conclusions.
Businesses operating multiple locations should also standardize their calculation methodology so management can make meaningful comparisons between outlets.
Prime Cost and Long-Term Profitability
Prime cost is closely connected to restaurant profitability, but it does not include every operating expense.
A business can maintain a relatively healthy prime cost while still facing financial pressure from rent, utilities, financing costs, or other fixed obligations.
For this reason, prime cost should be integrated into a broader financial management framework.
Regular monitoring helps restaurant owners understand whether cost increases are related to purchasing conditions, operational inefficiencies, or staffing decisions.
It also supports budgeting, pricing reviews, and the evaluation of operational improvements over time.
Conclusion
Restaurant prime cost is an essential metric for understanding the combined impact of food, beverage, and labor expenses on business performance.
By monitoring it consistently, operators gain better visibility into their cost structure and can make informed decisions about purchasing, staffing, and operational efficiency.
HORECA Plus supports restaurants, hotels, and hospitality businesses through financial analysis, cost control, and operational consulting, helping management teams develop reliable processes and strengthen financial performance.
To review your business’s cost structure and identify opportunities for improvement, contact HORECA Plus to arrange an introductory discussion.